General information about how home insurance claims commonly work in Alberta. Your own policy wording decides what's covered, so read it and ask your insurer or broker to confirm anything that matters to you.
Most people make a roof claim once or twice in their lives, usually right after a stressful storm. The process isn't complicated, but it has a set order, a few legal deadlines and a lot of paperwork, and it's easy to lose track.
This guide walks through an Alberta claim from the first phone call to closing the file. It's general information about how claims commonly work under Alberta's Insurance Act. Your own policy wording governs your claim, so keep it handy and check it at each step.
Before you start: find three things in your policy
Pull up your policy and the declarations page, which is the summary page listing your coverages, limits and deductibles. Find these three things before you talk to anyone:
- Your hail or wind deductible. Your policy may have a separate, higher deductible for hail or wind. It's usually a flat amount, though some policies use a percentage of your dwelling coverage. See hail deductibles in Alberta.
- How your roof is settled. Replacement cost, actual cash value, or a roof schedule based on age. This decides how much you're paid and when. See ACV vs RCV.
- Any time limits. Some policies set a deadline to finish repairs and claim money held back for depreciation.
The claim, in order
Timelines vary with the insurer and the size of the storm. After a city-wide event, everything takes longer. A year after the August 2024 Calgary hailstorm, CatIQ reported that nearly 85% of personal claims had been closed. Here's the order things usually happen in.
- Notify. Tell your insurer or broker about the damage as soon as you can, and follow up in writing. Get a claim number.
- Mitigate. Take reasonable steps to stop more damage, like tarping a leak or covering a broken window. Keep receipts.
- Document. Photograph the damage from the ground, note the date of loss, and gather any inspection report.
- Adjuster inspection. The insurer usually assigns an adjuster to inspect the damage and assess what the policy covers. Be there if you can.
- Scope of loss. The adjuster writes a scope, which is the list of what's damaged and what has to be repaired or replaced.
- Estimate. The scope is priced, line by line. Your contractor's estimate should be compared to it item by item.
- Proof of loss. You sign a sworn statement setting out the loss you're claiming. Your insurer or adjuster will usually provide the form.
- Settlement. The insurer pays, usually after taking off your deductible and any depreciation it's holding back.
- Completion. The work is done, and you send the final invoice and any completion paperwork the insurer asks for.
- Closing. Any recoverable depreciation is released, and the claim is closed.
What Alberta law requires
Alberta's Insurance Act sets out statutory conditions, which are rules the Act makes part of property insurance contracts in the province. They must be printed in the policy, and under the Act no variation, omission or addition to them is binding on you. These are the ones that matter most in a roof claim:
| Rule | What it says, in plain terms |
|---|---|
| Notice (Statutory Condition 6) | Give written notice to the insurer immediately after a covered loss. |
| Proof of loss (Statutory Condition 6) | Deliver a proof of loss, verified by statutory declaration, as soon as practicable. It states when and how the loss happened and the amount claimed. |
| Fraud (Statutory Condition 7) | Any fraud or wilfully false statement in the declaration invalidates the claim of the person who made it. |
| Salvage (Statutory Condition 9) | Take all reasonable steps to prevent further damage. The insurer contributes on a prorated basis to reasonable expenses for doing so. |
| Inspection (Statutory Condition 10) | The insurer has a right of access to inspect the property and estimate the loss. |
| Payment (Statutory Condition 12) | The loss is payable within 60 days after a completed proof of loss is delivered, unless the contract sets a shorter period. |
| Repair option (Statutory Condition 13) | Instead of paying, the insurer may repair or replace, if it gives written notice within 30 days of receiving the proof of loss. |
| Limitation (section 526) | A court action over loss or damage to insured property must start within 2 years after you knew or ought to have known about the damage. |
The adjuster, the scope and the estimate
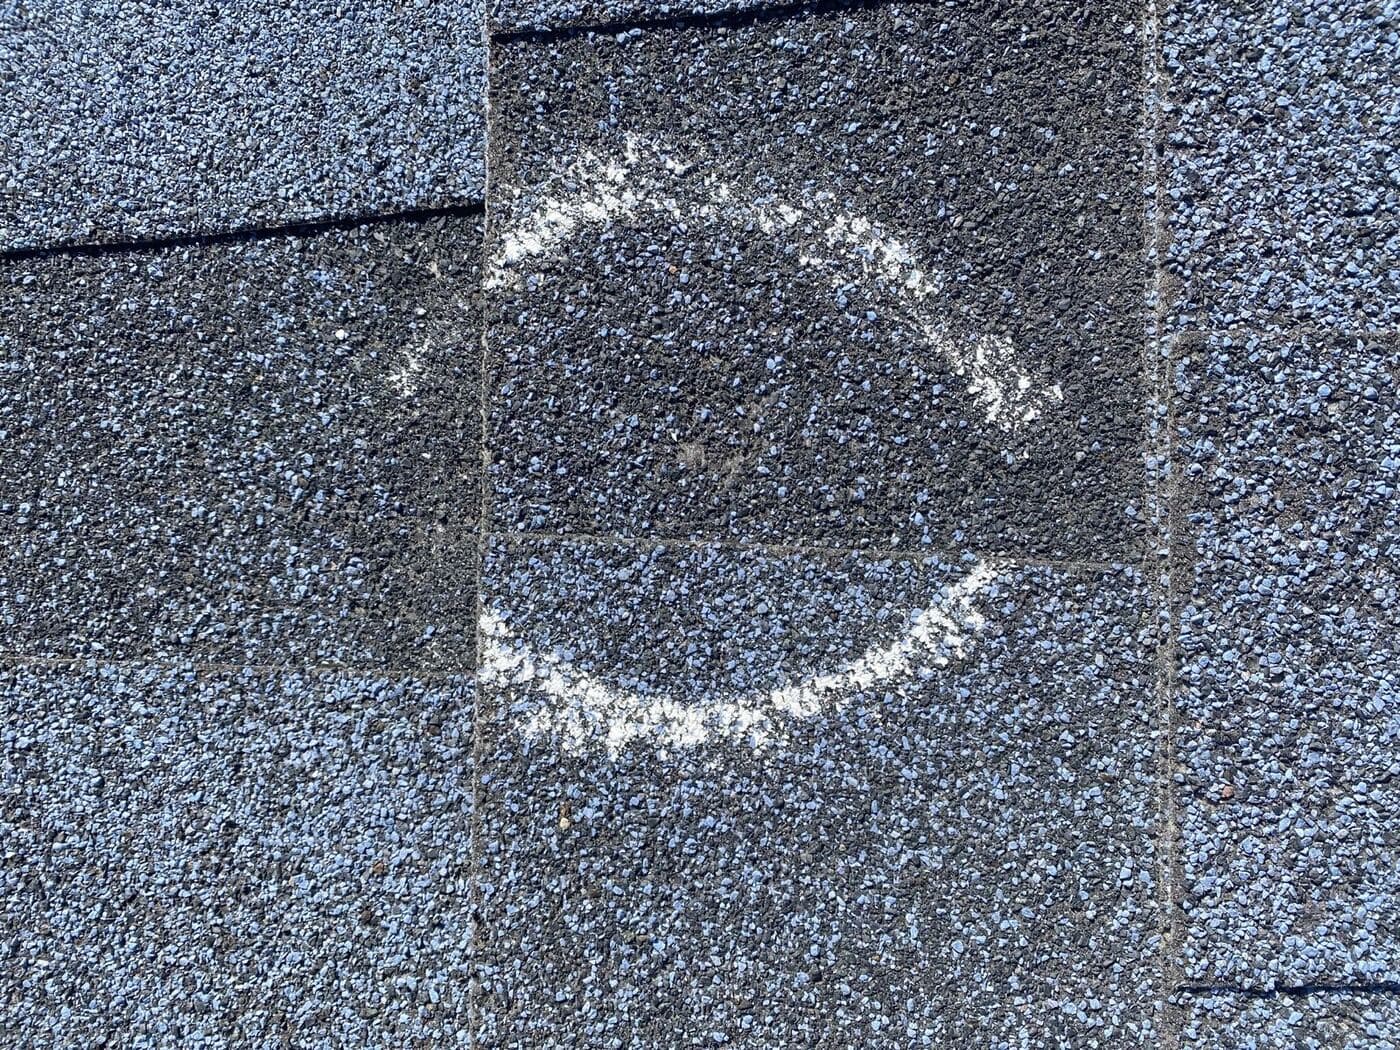
The adjuster's job is to confirm what happened, decide what your policy covers, and put a value on it. On a hail claim, that means looking at the shingles, but also the soft metals, vents, eavestroughs and siding that show how hard the storm hit. How adjusters assess hail explains the method.
When you get the adjuster's scope, read it next to your contractor's estimate, line by line. Often the gaps are items that were missed, like drip edge, vents, ice and water shield or a second slope, rather than true disagreements. Missing items are usually raised by sending more documentation and asking the adjuster to review, sometimes called a supplement. A well-documented inspection report, like the kind described in what is a HAAG report, makes that easier.
Getting paid: deductibles and depreciation holdbacks
The first payment is often smaller than people expect, and that doesn't automatically mean anything went wrong. Your deductible comes off. If your policy settles at replacement cost, the insurer may first pay the actual cash value, which is the replacement cost minus depreciation for age and wear, and hold back the rest.
That held-back amount is called recoverable depreciation. It's commonly paid once the repairs are finished and you've sent in the invoice. If the work never gets done, or the paperwork never gets sent, that money may never be paid. If you have a mortgage, the cheque may also be made out to your lender as well as you.
If you disagree
Start by asking questions and sending documentation. If you still disagree about the amount of the loss, or the repairs needed, Alberta's Insurance Act has a dispute resolution process. Either side can demand it in writing once the proof of loss has been delivered. Each side appoints a representative within 7 days, the two representatives choose an umpire within 15 days, and a written decision by any two of the three settles the question. Each side pays its own representative and shares the umpire's costs equally. The appraisal clause covers when that process is and isn't the right tool.
If the problem is how your claim was handled, the Government of Alberta directs people to the insurer's own complaint process first, then the General Insurance OmbudService. Concerns about the licensing or conduct of an agent, broker or independent adjuster go to the Alberta Insurance Council, and concerns about an insurance company's market conduct go to the Superintendent of Insurance. Where to complain walks through the order.
What to keep in your claim file
Keep one folder, paper or digital, for everything. It makes every conversation shorter and every dispute easier.
- Your policy wording, declarations page and claim number.
- The date of loss, with any weather warnings or news reports from that day.
- Dated photos and video of the damage, before and after temporary repairs.
- Receipts for emergency repairs, tarps and any other mitigation costs.
- Every inspection report, the adjuster's scope and your contractor's estimate.
- A copy of your signed proof of loss and the date you delivered it.
- All emails and letters, plus short notes of phone calls with the date, name and what was said.
- Settlement letters, cheques received, final invoices and proof you sent them in.
How long does a roof insurance claim take in Alberta?
It varies with the insurer and the size of the storm. Alberta's statutory conditions say the loss is payable within 60 days after a completed proof of loss is delivered, unless the policy sets a shorter period. After a large storm, inspections and repairs can stretch over months.
What is a proof of loss?
A sworn statement, verified by statutory declaration, that sets out when and how the loss happened and what you're claiming. Alberta's statutory conditions require it as soon as practicable, and a wilfully false statement in it can invalidate your claim.
How long do I have to make a home insurance claim in Alberta?
Report damage right away, since the statutory conditions require immediate written notice. Separately, a court action over an Alberta property claim generally has to start within 2 years of when you knew or ought to have known about the damage. Check your policy for other time limits, such as deadlines to claim depreciation.
Why was my first insurance cheque so small?
Usually because the deductible came off and the insurer is holding back depreciation until the work is finished. Check the settlement letter for a recoverable depreciation amount before assuming you were underpaid.
Can my roofer deal with my insurance company for me?
You stay the policyholder, and you'll normally sign your own proof of loss. Many homeowners handle the claim themselves and share the contractor's report and estimate with the insurer. If you want someone else to speak with your insurer, ask the insurer what written authorization it needs.
Where the facts on this page come from. If a source has changed since we last checked, tell us and we'll fix the page.
- Insurance Act, RSA 2000, c I-3 (ss. 519, 526 and 540) · Alberta King's Printer
- Insurance consumer complaints · Government of Alberta
- Hail and insurance · Insurance Bureau of Canada
- Insurance 101: The insurance claims process · General Insurance OmbudService
- Home insurance · Financial Consumer Agency of Canada
- CAD 3.29B: CatIQ discloses updated industry loss for the Calgary hailstorm of August 5, 2024 · CatIQ