INSURANCECLAIMS.
How Alberta roof claims actually work, from first call to final cheque.
- GUIDES
- 7
- GLOSSARY TERMS
- 27
A roof claim is a contract question as much as a roofing one. Your policy decides what's covered, how depreciation is handled, what your deductible is and what happens if you disagree with the adjuster. Most homeowners read it for the first time after the storm.
This shelf walks the whole process in order and explains the words you'll hear along the way. It's general information about how claims commonly work in Alberta. Your own policy wording is what actually applies.
- What are the steps of a roof insurance claim?
- How do hail deductibles work?
- What's the difference between ACV and RCV?
- What can I do if I disagree with the adjuster?
READ THEM IN THIS ORDER.
- 01The roof insurance claim, step by stepAn Alberta roof claim goes in a set order: tell your insurer in writing, stop further damage, document everything, get the roof inspected, agree the scope and estimate, file a sworn proof of loss, then settle and repair. Once a completed proof of loss is delivered, Alberta law says the loss is payable within 60 days unless your policy sets a shorter period.
- 02Hail deductibles in Alberta: flat, percentage and why they've gone upMany Alberta home policies now carry a separate hail deductible, usually a flat amount: industry reports in 2026 put it at $2,500 to $5,000 with many Calgary insurers, and up to $10,000 for homes without hail-resistant construction. Percentage deductibles exist but are less common here, and your hail deductible can change at renewal, so check your declarations page.
- 03ACV vs RCV Roof Coverage in AlbertaActual cash value (ACV) pays what your damaged roof was worth after age and wear; replacement cost value (RCV) pays what it costs to replace it. Many Alberta RCV policies pay the ACV amount first and release the held-back depreciation only after the work is done and invoiced, so the first cheque is often not the full settlement.
THE BASICS
Plain-language primers. Assume nothing.
DEEP DIVES
For when you're mid-decision, mid-claim or mid-argument.
Hail deductibles in Alberta: flat, percentage and why they've gone up
Many Alberta home policies now carry a separate hail deductible, usually a flat amount: industry reports in 2026 put it at $2,500 to $5,000 with many Calgary insurers, and up to $10,000 for homes without hail-resistant construction. Percentage deductibles exist but are less common here, and your hail deductible can change at renewal, so check your declarations page.
ACV vs RCV Roof Coverage in Alberta
Actual cash value (ACV) pays what your damaged roof was worth after age and wear; replacement cost value (RCV) pays what it costs to replace it. Many Alberta RCV policies pay the ACV amount first and release the held-back depreciation only after the work is done and invoiced, so the first cheque is often not the full settlement.
How Insurance Adjusters Assess Hail Damage
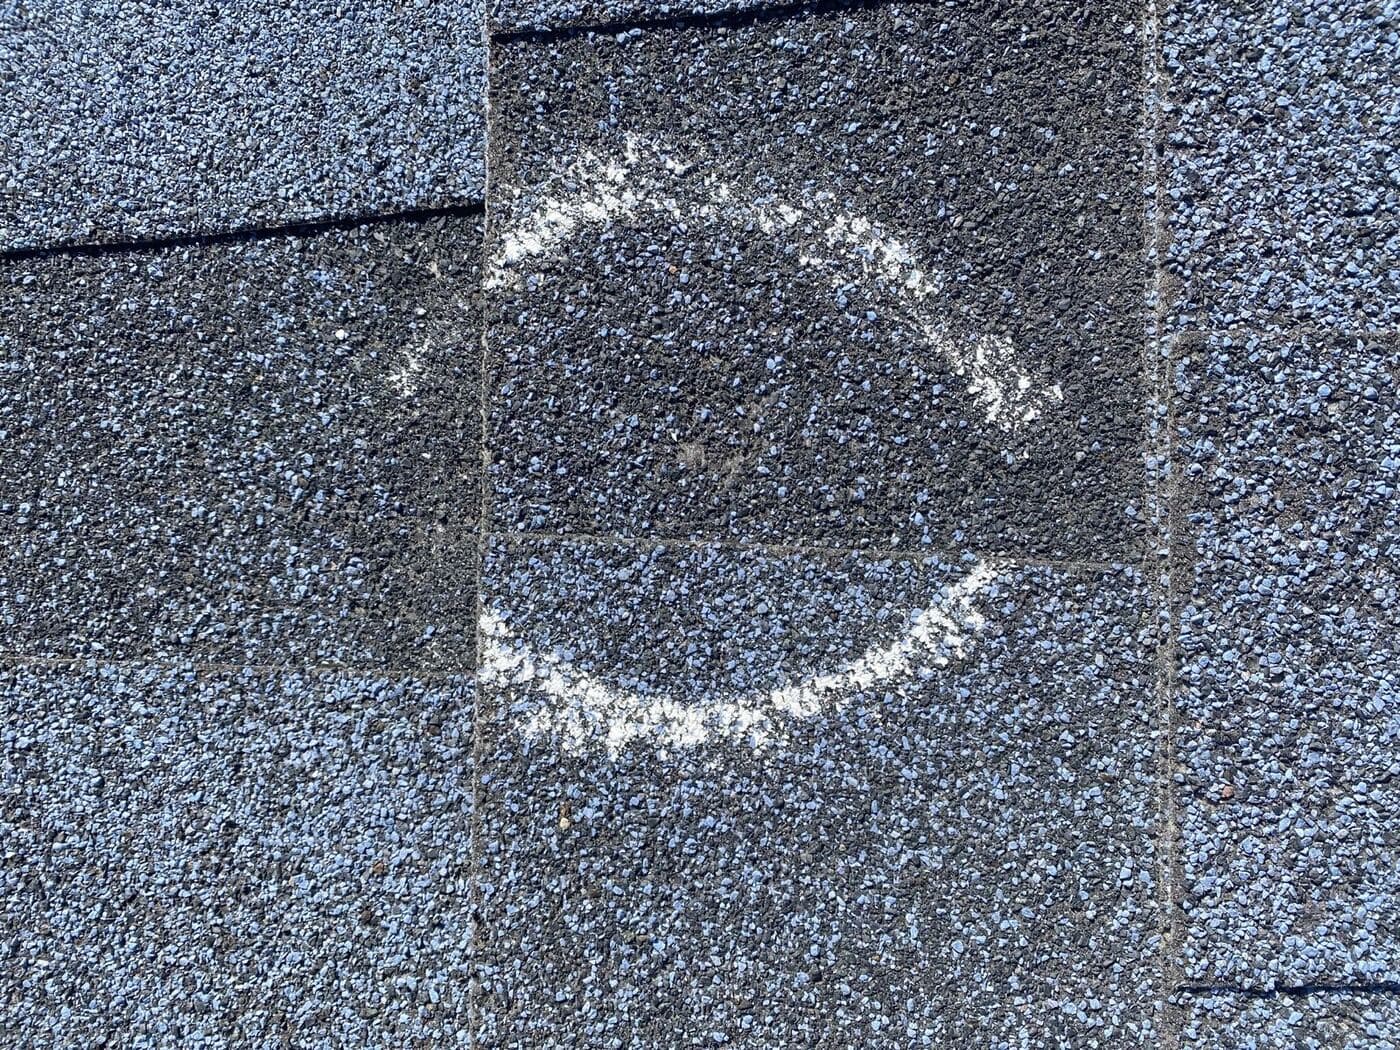
An adjuster is checking for functional hail damage, meaning damage that shortens the roof's life or lets water in, not just marks. They sample each slope with a test square, count the hits, check soft metals like gutters and vents for dents, and compare what they find against the insurer's threshold for replacement.
What a HAAG Inspection Report Contains
A HAAG inspection report documents roof damage to Haag's published methodology: a slope diagram, test squares, scaled photos, soft-metal damage and an itemized scope, so an adjuster can check each finding instead of taking a conclusion on trust. Haag certifies inspectors, not companies.
The Appraisal Clause: Disputing a Roof Claim in Alberta
If you and your insurer agree the damage is covered but disagree on what it costs to fix, Alberta's Insurance Act gives you a dispute process, often called appraisal: each side names a representative, the two pick an umpire, and they settle the amount without court. It decides the dollar figure, not whether something is covered.
Where to Complain About a Roof Claim in Alberta
Complain in order: first your insurer's own complaints officer, until you get a final position letter; then the General Insurance OmbudService; and the Alberta Insurance Council for the conduct of agents, brokers or independent adjusters. Complaints about a contractor go to Service Alberta's Consumer Investigations Unit instead.
THE INSURANCE CLAIMS GLOSSARY.
- Actual cash value
- What damaged property was worth at the time of loss: the cost to replace it minus depreciation for age and wear. Often shortened to ACV.
- Adjuster
- The person who investigates an insurance claim and assesses the damage and the amount of the loss. They may work for the insurer or for an independent firm.
- Appraisal clause
- A policy provision for settling a disagreement over the amount of a covered loss using appraisers and an umpire. It doesn't decide whether something is covered in the first place.
- Assignment of benefits
- An agreement that hands some of your insurance claim rights or payments to someone else, such as a contractor. Read one carefully before signing.
- Collateral damage
- In a hail claim, dents and marks on soft metals and other items around the property, such as eavestroughs, vents and fence caps, that help show hail size and direction.
- Cosmetic damage
- Marks or dents that change how something looks without affecting how it performs. Some policies exclude it.
- Cosmetic damage exclusion
- Policy wording that excludes damage affecting only appearance, such as hail dents in metal roofing that don't let water in. Whether it applies depends on the insurer and the policy.
- Date of loss
- The date the damage happened, as recorded on an insurance claim. When several storms could have caused damage, establishing the date can matter a great deal.
- Declarations page
- The summary page of an insurance policy listing who and what is insured, the coverage limits, the deductibles and the policy period.
- Deductible
- The part of a covered loss you pay yourself before insurance pays. It's usually subtracted from the claim payment.
- Depreciation
- The reduction in value an insurer applies for the age and wear of damaged property.
- Dwelling limit
- The most your home policy will pay for the house itself, shown on your declarations page and sometimes called Coverage A. It isn't your home's market value, and a percentage deductible is usually calculated from it.